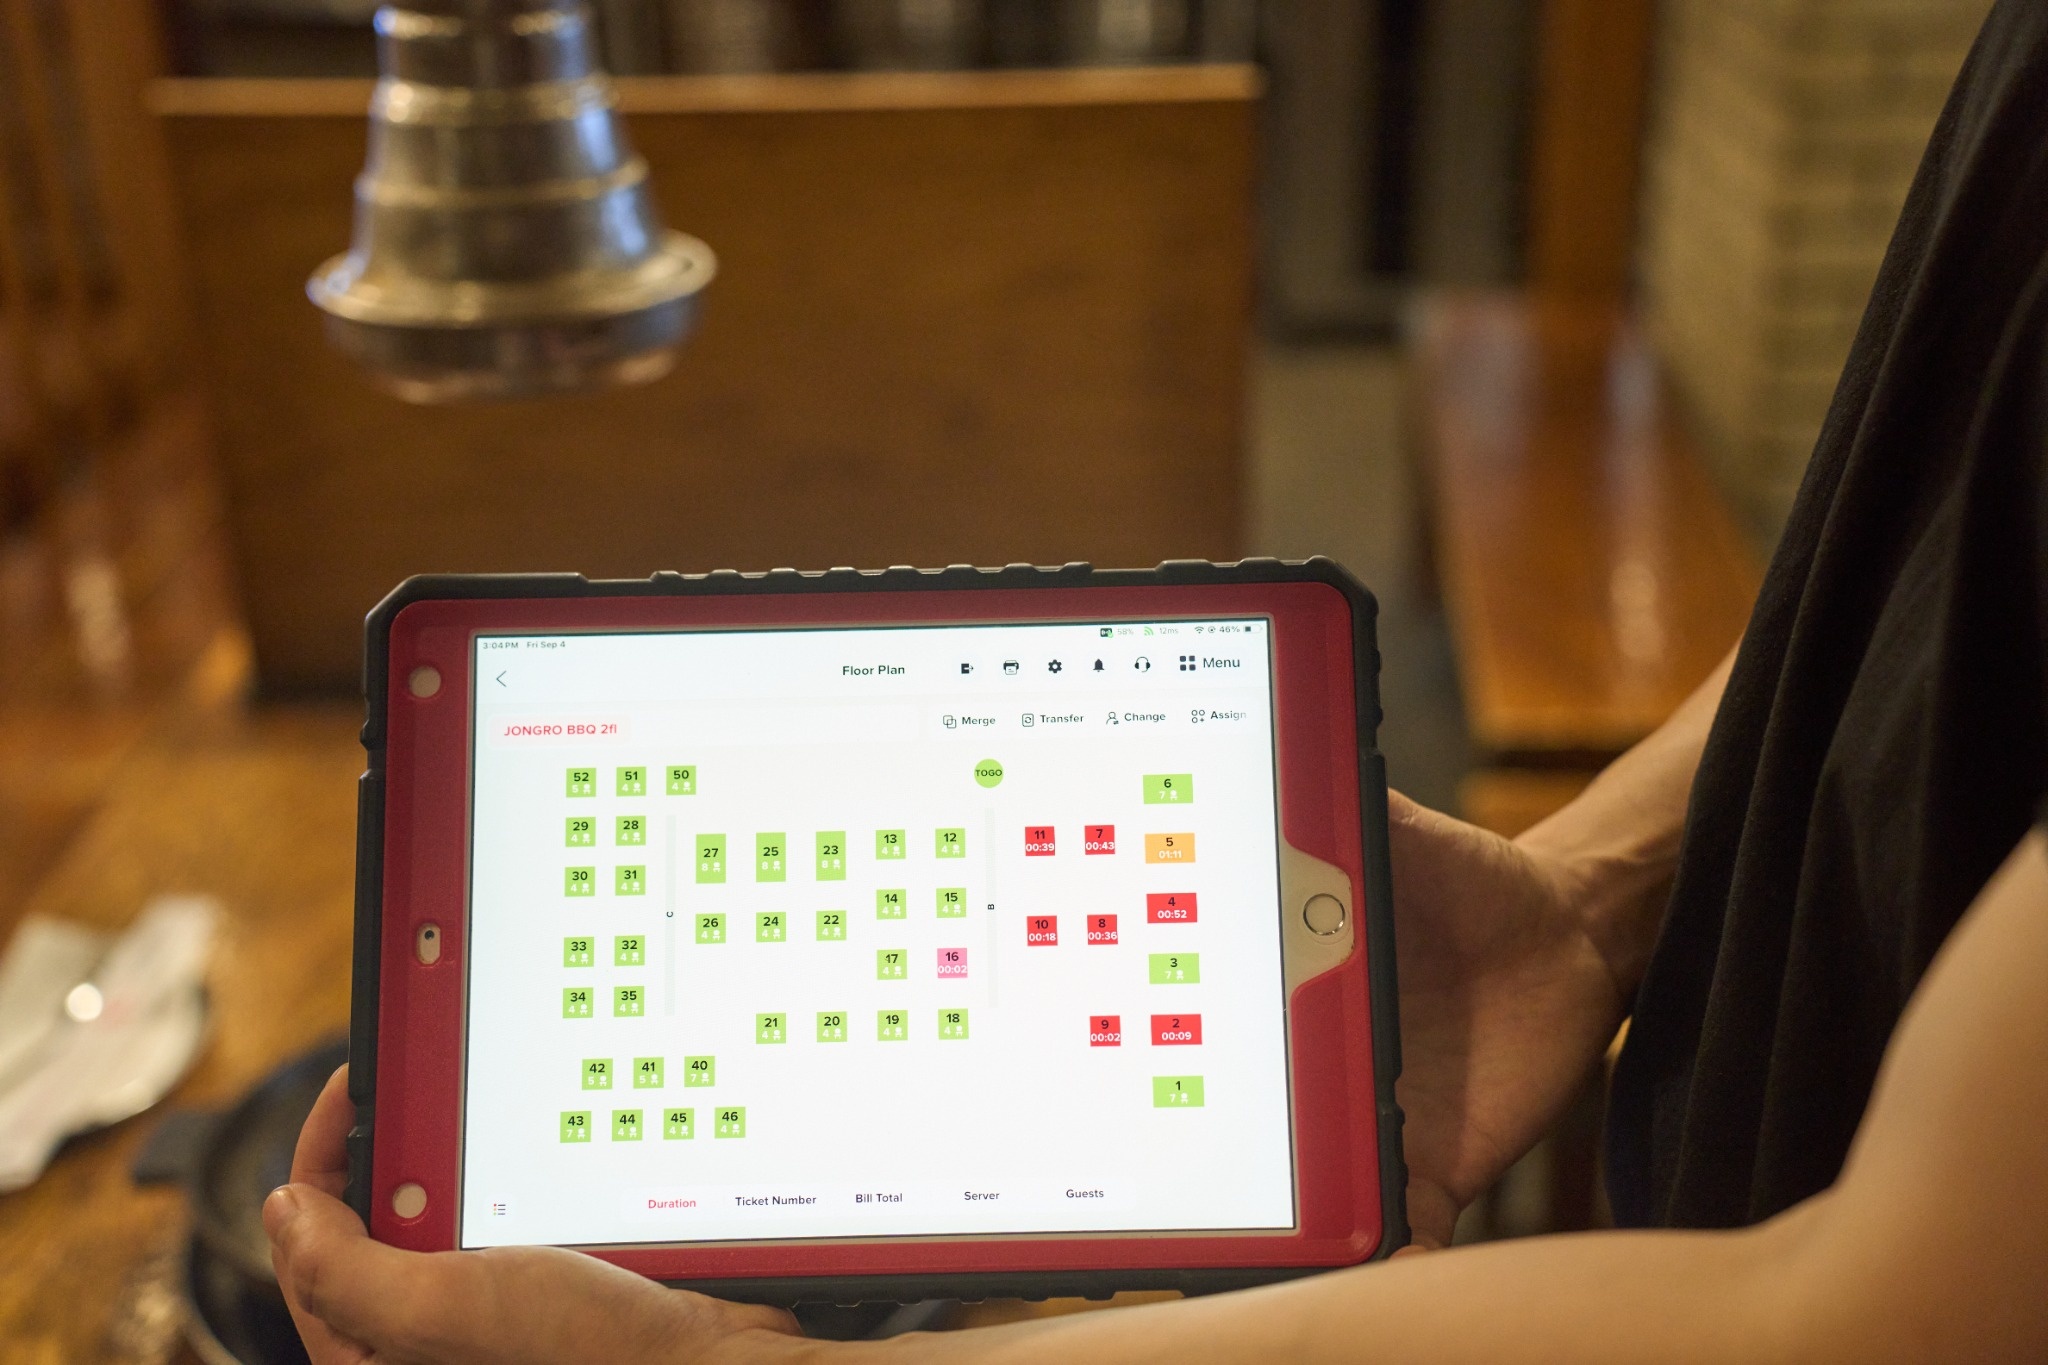
A sales rep walks into a busy dumpling house and makes an offer that sounds too good to pass up: "You'll never pay a card processing fee again." The owner has been watching processing costs climb every month, and the pitch lands. What the rep means, though, is that the fee is still charged on every card swipe. It just moves from the restaurant's statement to the guest's receipt.
Programs sold as "free payment processing" or "zero-fee processing" are real, legal in most places, and the right choice for some restaurants. They also come with card network rules, state laws, and guest reactions that the pitch rarely covers. This guide explains how cash discounting and surcharging actually work, what each one costs the restaurant and the guest, and what to check before you put a new line on your receipts.
Every card payment has a cost. The guest's bank, the card network, and the processor each take a share, and that money comes out of the transaction no matter what the program is called. A "free" processing program shifts those costs onto the guest.
There are two common ways to do that. With a surcharge, your menu shows the regular price and a fee is added when a guest pays by credit card. With a cash discount, your menu shows a slightly higher card price, and guests who pay cash get a discount at checkout. A third approach, often called dual pricing, shows both a cash price and a card price for every item.
From a math standpoint, the three can land on similar totals. From a rules standpoint, they are treated very differently, and that difference is where most restaurants get into trouble.
Take a table whose food and drinks come to $50 before tax and tip, and assume a fee of 3% for illustration. Under a surcharge program, the menu prices add up to $50, and a guest paying by credit card sees a separate line for $1.50. A guest paying cash pays $50.
Under a cash discount program, the menu prices are set about 3% higher, so the same order shows $51.50. A guest paying by card pays $51.50. A guest paying cash sees a discount line and pays $50.
Under dual pricing, the menu shows both numbers next to each item, and the receipt reflects whichever one the guest chose. The totals in all three cases are close. What changes is what the guest sees first and what rules apply to you.
If you add a fee for credit card payments, you are surcharging, and the card networks have specific rules for it. Visa caps credit card surcharges at 3% and, like Mastercard, limits them to your actual cost of acceptance. Surcharges are not allowed on debit cards or prepaid cards, even when the guest runs a debit card as credit. That means a surcharge program cannot recover processing costs on debit transactions, which are a large share of card payments at many casual restaurants.
The networks also expect advance notice. Before you start surcharging, you generally need to notify your processor, which handles the notice to the card brands, typically at least 30 days ahead. The surcharge has to be disclosed to guests at the entrance and at the point of sale, and it has to appear as its own line on the receipt. Card brands do audit merchants, and penalties for noncompliant surcharging can be passed down to the restaurant.
One detail that catches restaurants: posting your lower price and then adding a "card fee" at the register is treated as a surcharge, even if your processor calls the program a cash discount. A true cash discount starts from the card price and takes money off for cash.
State rules sit on top of card network rules, and they change. Connecticut and Massachusetts prohibit credit card surcharges, though cash discounts are permitted. Colorado limits surcharges to 2%. New York allows surcharges but requires businesses to post the total price that includes the surcharge, so a sign at the register and a fee line on the receipt is no longer enough there. California's 2024 rules on mandatory fees require restaurants to disclose any added charge clearly on the menu.
Because these laws are amended regularly, treat any list you read, including this one, as a starting point. Check your state attorney general's website and ask your processor to confirm, in writing, that their program is set up for the state where your restaurant operates. If you run locations in more than one state, check each one separately.
Tips are where the numbers in "zero-fee" programs often stop adding up. When a guest adds a 20% tip on a card, the processor charges a fee on the full amount, tip included. Many surcharge and cash discount setups calculate the fee on the pre-tip subtotal. The processing cost on the tip portion stays with the restaurant.
For a full-service restaurant where tips are a large part of card volume, that leftover cost is noticeable. Ask the processor exactly how the program handles tips, then look at one month of statements after launch to see whether your total processing cost actually went to zero. If you are not sure how to read those statements, this walkthrough of a restaurant payment processing statement covers each section.
Guests notice extra lines on receipts, and they mention them in reviews. Some don't mind a clearly posted card fee, especially at counter-service spots with low checks. Others feel caught off guard, particularly when the fee shows up only at the end of the meal. A family celebrating a birthday with a $180 hot pot dinner may not notice a 3% fee until the check arrives, and that moment shapes how they remember the night.
A few practices reduce the friction. Disclose the program where guests will actually see it: at the door, on the menu, and on any online ordering page. Train servers to explain it in one sentence without apologizing. Make the receipt wording plain, such as "Cash discount applied" or "Credit card surcharge," rather than a vague label like "service adjustment." If you serve many regulars or older guests, watch your reviews in the first two months and be ready to adjust.
Even with a program that recovers most card fees, some costs stay on your side of the ledger. Debit card transactions under a surcharge program are one. Tips are another. Many "free processing" offers also carry monthly software fees, terminal leases, or long contracts with early termination fees, and those deserve the same attention as the processing rate.
There is also the cost of your menu. A cash discount program usually means raising posted prices by a few percent across the board. Guests comparing your menu online with a nearby competitor will see the higher number. For some restaurants, that matters more than the processing savings.
A cash discount or surcharge program tends to fit restaurants with a high share of card payments, thin margins, and lower average checks, where guests are less sensitive to a small fee. Quick-service shops, bubble tea stores, and bakeries often fall into this group. It fits less well at full-service restaurants where the guest experience at the end of the meal carries a lot of weight, or in states where the rules make surcharging impractical.
Before you decide, run your own numbers. Pull three months of statements and calculate your current effective rate. Estimate how much of your card volume is debit, and how much is tips. Then ask each provider to show what your monthly cost would be under their program using your real volume. Comparing that number with what you pay today gives you a clearer answer than any sales pitch. For a broader look at how processing pricing works, see this restaurant payment processing guide.
Q1: Is free payment processing really free for restaurants?
No. The processing fee is still charged on every card payment. A "free" program moves the fee to guests through a surcharge or a cash discount, and some costs, such as fees on tips or debit cards, may still fall on the restaurant.
Q2: What is the difference between a cash discount and a surcharge?
A surcharge adds a fee to the posted price when a guest pays by credit card. A cash discount starts from a posted card price and takes money off when a guest pays cash. They are governed by different card network rules and state laws.
Q3: Is it legal for a restaurant to charge a credit card surcharge?
In most states, yes, as long as you follow card network rules, including the 3% Visa cap and the ban on surcharging debit cards. Some states, such as Connecticut and Massachusetts, prohibit surcharges, and others set caps or disclosure rules, so check your state before starting.
Q4: Can I add a surcharge to debit card payments?
No. Card network rules do not allow surcharges on debit or prepaid cards, even when the card is run as credit. A cash discount program handles debit differently because the posted price is the card price.
Q5: Do surcharge programs cover the processing fee on tips?
Often they do not. Many programs calculate the fee on the subtotal before the tip, so the processing cost on the tip amount stays with the restaurant. Ask your processor how tips are handled before you sign.
Q6: How should a restaurant tell guests about a cash discount or surcharge?
Post it at the entrance, on the menu, and on online ordering pages, and show it as a clearly labeled line on the receipt. Give staff a short, plain explanation they can use when guests ask.
Programs marketed as free processing still pay the card networks on every transaction; the guest covers that cost instead of the restaurant. For the right restaurant, moving that cost to the guest is a reasonable choice that can protect margins. For another restaurant, the added rules, the remaining costs on tips and debit, and the effect on guests can outweigh the savings.
Look at your own statements, your state's rules, and the kind of experience your guests expect at the end of a meal. If a program still makes sense after that, set it up carefully, disclose it plainly, and check your first two months of statements to confirm the savings are real.